
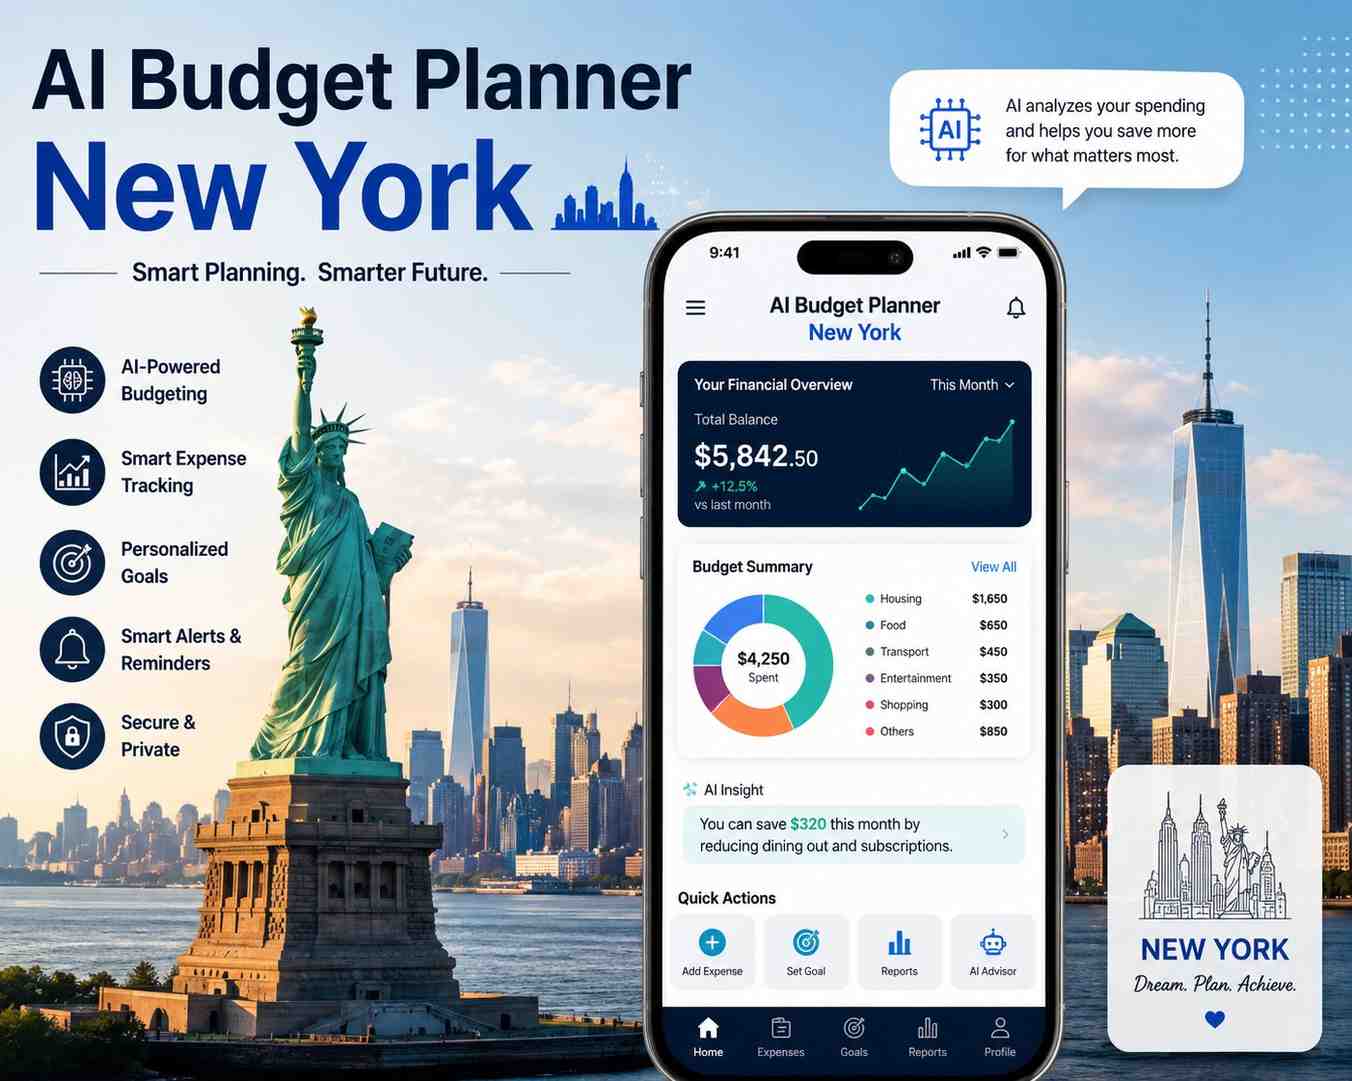
Living in New York City can be financially rewarding, but managing money here requires more than simply tracking your monthly income and expenses. Rent, groceries, transportation, healthcare, childcare, debt payments, and everyday purchases can quickly consume a large portion of your paycheck.
Whether you live in Manhattan, Brooklyn, Queens, the Bronx, or Staten Island, having a realistic monthly budget can help you understand where your money goes and how much you can actually afford to save.
Our AI Budget Planner New York helps you organize your finances, estimate your monthly spending, evaluate rent affordability, plan debt payments, and set practical savings goals. Instead of relying on a generic budgeting formula, you can enter your own financial information and build a plan around your circumstances.
You do not need to connect a bank account or share financial credentials. Enter your figures into the calculator to explore different budgeting scenarios.
What Is an AI Budget Planner?
An AI budget planner is a financial planning tool designed to help people organize income, expenses, savings, and debt obligations. Depending on the product, it may use artificial intelligence, automated transaction categorization, forecasting, or predefined financial rules to generate recommendations.
For someone living in New York, a useful budget planner should consider more than a monthly salary. It should account for housing costs, transportation choices, household size, recurring bills, and financial priorities.
For example, someone renting an apartment in Manhattan may have a very different spending pattern from a family living in Queens or a commuter living in Staten Island.
Our New York Budget Planner uses editable financial inputs and automated budgeting calculations to help you understand your monthly cash flow. Its recommendations are generated using financial rules rather than a connected generative AI service. This means your calculations can run directly in your browser without sending your financial information to an external AI provider.
Use Our Free AI Budget Planner New York
Enter your monthly take-home income, housing expenses, groceries, transportation costs, debt payments, and savings goals. The calculator will estimate your available balance and show how your money is allocated.
AI Budget Planner New York
Create a personalized monthly budget, understand your spending, plan savings and explore your financial future.
1. Your Income Information
Enter your regular income. Use take-home pay or enter gross pay with estimated deductions.
2. Monthly Housing Expenses
Include the actual amount you pay each month.
3. Daily Living Expenses
Enter your average monthly spending.
4. Debt & Savings Goals
Include required monthly debt payments and the amount you want to save.
5. Budgeting Preferences
Choose a starting budget method. You can change the percentages.
Your Monthly Budget Summary
Based on your entered financial information.
Budget Health Score
An educational indicator based on the figures you entered, not a credit score or financial assessment.
Monthly Spending Breakdown
See how much of your take-home income goes toward each category.
Rent Affordability Analysis
50/30/20 Budget Comparison
| Category | Suggested Amount | Your Actual Amount | Difference |
|---|
Emergency Fund Planner
Future Savings Projection
An illustrative projection using your desired monthly savings and assumed annual return.
Your Personalized Action Plan
Important: This is an educational budgeting calculator, not a tax calculator or a substitute for professional financial advice. Tax deductions must be entered by the user. Savings projections are hypothetical and are not guaranteed. Borough selection does not automatically apply local cost estimates.
The calculator is designed for individuals, couples, families, employees, freelancers, and people with irregular income.
You can change your figures to compare different situations. For example, you might want to see what happens if your rent increases, you pay off a credit card, or your monthly income changes.
How to Create a Monthly Budget in New York
Creating a realistic budget starts with understanding how much money you actually receive and how much you need to spend.
1. Calculate Your Monthly Take-Home Income
Start with the amount deposited into your bank account after payroll deductions.
If your annual salary is $72,000, your gross monthly salary is $6,000. However, that does not mean you have $6,000 available to spend.
Your actual paycheck may be reduced by:
- Federal income tax.
- New York State income tax.
- New York City resident income tax, if applicable.
- Social Security and Medicare taxes.
- Health insurance premiums.
- Retirement contributions.
- Other payroll deductions.
Your filing status, deductions, benefits, and withholding elections can change your take-home pay.
New York State updated its 2026 withholding tables and methods. Therefore, use current payroll information when planning your actual spending rather than relying on an old online salary estimate.
Official reference: New York State Department of Taxation and Finance.
Practical tip: If you already know your regular net paycheck, use that figure in the budget planner. It is generally more useful for everyday spending decisions than an estimated gross-to-net calculation.
2. Understand Your New York Housing Costs
Housing is often one of the largest expenses in a New York household budget.
Your housing costs may include:
- Monthly rent or mortgage payments.
- Electricity and gas.
- Water charges, where applicable.
- Internet and mobile service.
- Renter’s or homeowner’s insurance.
- Parking and building-related expenses.
- Moving and apartment setup costs.
A commonly used affordability benchmark is to keep housing costs around 30% of gross household income. However, this is a guideline, not a guarantee that an apartment will be affordable.
For example, someone earning $6,000 in gross monthly income may use $1,800 as an initial 30% housing benchmark. But that person must still account for taxes, debt, healthcare, transportation, and other obligations.
New York City has substantial differences between neighborhoods and boroughs. A realistic housing budget should use the actual rent you expect to pay rather than assuming every part of the city has the same housing costs.
3. Compare Living Costs Across NYC Boroughs
The five boroughs of New York City offer different housing choices, commuting patterns, and everyday spending opportunities.
Manhattan
Manhattan offers access to many workplaces, services, restaurants, and subway connections. However, apartment location, building amenities, and proximity to employment can have a major impact on total housing costs.
When planning a Manhattan budget, consider rent, groceries, dining, transportation, and the additional cost of convenience purchases.
Brooklyn
Brooklyn includes a wide variety of neighborhoods and housing options. Your budget may change considerably depending on whether you live close to major subway lines, commute to Manhattan, or work locally.
Remember to account for commuting costs and the distance between your home and workplace.
Queens
Queens has many different residential communities, transportation arrangements, and household types. Some residents commute to Manhattan, while others work within the borough.
Your transportation budget should reflect your actual commute rather than an assumed monthly amount.
The Bronx
The Bronx offers different housing and commuting options. Families should also account for childcare, healthcare, school-related expenses, groceries, and transportation when calculating their monthly needs.
Staten Island
Staten Island residents may have different transportation requirements depending on their workplace and daily travel arrangements. Car ownership, fuel, insurance, parking, and public transportation may all affect the monthly budget.
The important point is that choosing a borough alone cannot determine your cost of living. Neighborhood, household size, housing arrangement, and personal spending habits matter too.
4. Organize Your Monthly Expenses
Once you know your take-home income, divide your spending into clear categories.
Housing: Rent, mortgage, utilities, insurance, and maintenance.
Food: Groceries, restaurants, coffee, and food delivery.
Transportation: Subway, bus, commuter rail, fuel, parking, car insurance, and vehicle maintenance.
Healthcare: Health insurance premiums, prescriptions, dental care, and out-of-pocket medical expenses.
Personal expenses: Clothing, entertainment, subscriptions, fitness, and personal care.
Family expenses: Childcare, education, school supplies, and other dependent-related costs.
Debt payments: Credit cards, student loans, personal loans, and vehicle financing.
Savings: Emergency savings, retirement contributions, future purchases, and other financial goals.
Do not forget irregular expenses. Annual insurance premiums, holiday purchases, car repairs, and medical bills can make an otherwise balanced monthly budget look inaccurate.
One practical method is to estimate the annual cost of each irregular expense and divide it by 12. This creates a monthly planning amount.
5. Should You Follow the 50/30/20 Budget Rule?
The 50/30/20 method is a popular budgeting framework that divides after-tax income into three broad groups.
| Budget category | Suggested allocation |
|---|---|
| Needs | 50% |
| Wants | 30% |
| Savings and debt goals | 20% |
Suppose your monthly take-home income is $5,000.
- Needs: $2,500.
- Wants: $1,500.
- Savings and debt goals: $1,000.
This is a starting framework, not a rule that every New Yorker must follow.
In a high-cost housing market, essential expenses may consume more than 50% of your take-home pay. If that happens, forcing your budget into the standard percentages can create an unrealistic plan.
Instead, calculate your essential expenses first. Then decide how much you can reasonably allocate to discretionary purchases and savings.
A custom budget is often more useful than a perfect-looking percentage breakdown.
6. Plan Your Transportation Expenses
Transportation can have a significant impact on your monthly spending.
New Yorkers may use:
- Subway services.
- Local buses.
- Express buses.
- Commuter rail services.
- Ferries.
- Personal vehicles.
- Rideshare and taxi services.
- Walking or cycling.
If you use public transportation regularly, check the latest official fares and fare-capping arrangements before calculating your monthly commuting budget.
For car owners, include more than fuel. Insurance, parking, maintenance, registration, tolls, repairs, and financing can all affect the real monthly cost of owning a vehicle.
Official information: MTA fares and tolls.
A useful approach is to compare your actual commuting expenses over the last two or three months. This is more reliable than entering a random transportation estimate.
7. Build an Emergency Fund
An emergency fund helps protect your household against unexpected financial problems.
Possible emergencies include:
- Losing your job.
- Unexpected medical expenses.
- Urgent home repairs.
- Vehicle repairs.
- Reduced working hours.
- Temporary income interruptions.
A common starting target is three to six months of essential expenses. Households with irregular income, dependents, or less predictable employment may prefer a larger reserve.
For example, if your essential monthly expenses are $3,200:
| Emergency fund target | Savings goal |
|---|---|
| 1 month | $3,200 |
| 3 months | $9,600 |
| 6 months | $19,200 |
| 12 months | $38,400 |
These are mathematical targets, not mandatory savings requirements.
If you cannot save a large amount immediately, start with a smaller achievable goal. Consistent contributions can gradually build a financial safety net.
8. Manage Credit Card and Student Loan Debt
Debt payments can reduce the amount of money available for rent, groceries, savings, and other priorities.
Begin by listing each debt separately:
- Current outstanding balance.
- Annual percentage rate (APR).
- Minimum monthly payment.
- Due date.
- Additional amount you can afford to pay.
Two common repayment approaches are the debt avalanche and debt snowball methods.
Debt avalanche: Pay minimum amounts on all debts and direct additional money toward the debt with the highest interest rate. This can reduce total interest costs when followed consistently.
Debt snowball: Pay minimum amounts on all debts and focus extra money on the smallest balance first. This may provide motivational progress.
Continue making all required minimum payments. Do not allocate money to additional debt repayment if it leaves you unable to cover essential expenses.
For federal student loans, review your current repayment options and eligibility through the official Federal Student Aid website.
9. Understand New York Financial Assistance Programs
Budgeting is not only about reducing expenses. Some households may qualify for public programs that help cover essential needs.
New York City provides access to resources related to:
- Affordable housing.
- Food assistance.
- Healthcare.
- Childcare.
- Public benefits.
- Emergency support.
The city’s ACCESS NYC service allows residents to screen for more than 30 assistance programs.
Visit ACCESS NYC to explore programs based on your household and circumstances.
The NYC Affordability Resources page also provides information about housing, food, health, transportation, and childcare resources.
Eligibility requirements, application procedures, and benefit amounts vary. A budget calculator cannot determine your official eligibility.
10. Use the 2026 NYC True Cost of Living Measure
One important development for New York households is the city’s True Cost of Living Measure.
Unlike a basic expense calculator, this measure considers a broader picture of financial security, including housing, food, healthcare, childcare, transportation, technology, savings, taxes, and available resources.
The 2026 measure provides an important framework for understanding why two households with similar incomes may experience very different financial pressures.
For example, a household with children may have substantial childcare expenses, while a single adult may spend more on housing relative to household income.
This is why a personalized budget should consider household composition instead of applying the same expense assumptions to everyone.
Read the official NYC True Cost of Living information.
11. How Much Money Should You Save Each Month in New York?
There is no single savings amount that works for every New Yorker.
Your savings capacity depends on:
- Monthly take-home income.
- Housing expenses.
- Household size.
- Debt obligations.
- Healthcare expenses.
- Employment stability.
- Short-term and long-term goals.
Rather than choosing an arbitrary savings target, calculate the money remaining after essential expenses and required debt payments.
Then divide your savings goals into separate purposes.
Emergency savings: Money reserved for unexpected expenses.
Short-term savings: Money for travel, education, electronics, or planned purchases.
Long-term savings: Money for retirement or other future financial objectives.
If your current budget does not allow meaningful savings, identify the largest flexible expenses first. Small recurring costs can add up over time.
12. How to Make Your NYC Budget More Flexible
A budget should change when your circumstances change.
Consider creating three financial scenarios.
Scenario 1: Normal month
Use your regular take-home income and expected monthly expenses.
Scenario 2: Higher expenses
Increase rent, groceries, transportation, or utility costs to understand how much financial pressure you could face.
Scenario 3: Lower income
Reduce your expected income to simulate fewer working hours, reduced freelance work, or a temporary income interruption.
This approach can help identify how much flexibility you have before a financial problem occurs.
You can also review your spending every month and update your budget when your lease, salary, debt payments, or household situation changes.
Common New York Budgeting Mistakes to Avoid
Even people with good incomes can experience financial pressure when their spending plan does not reflect their actual lifestyle.
Here are some mistakes worth avoiding:
- Using gross salary as spending money: Your take-home income is the amount that matters for everyday budgeting.
- Ignoring irregular expenses: Annual and unexpected costs should be included in your planning.
- Underestimating transportation: Car ownership and commuting can cost more than the basic fare.
- Forgetting subscriptions: Review recurring digital services and memberships regularly.
- Setting unrealistic savings goals: An achievable monthly target is more useful than an ambitious target you cannot maintain.
- Ignoring debt interest: Minimum payments alone may not reduce high-interest balances quickly.
- Using outdated tax information: Payroll withholding and tax rules can change.
- Assuming every borough has the same costs: Housing and commuting expenses vary by location and personal circumstances.
Frequently Asked Questions
Is there a free AI Budget Planner for New York?
Yes. You can use the free AI Budget Planner on NewYorkCalculator.com to organize your monthly income, housing expenses, transportation, debt, and savings goals. The calculator uses automated budgeting rules and does not require bank-account access.
How much money do I need to live comfortably in New York City?
There is no universal income requirement. Your needs depend on where you live, whether you rent or own, household size, healthcare, childcare, transportation, and lifestyle. Calculate your actual monthly expenses before deciding whether a salary is sufficient.
What is the 50/30/20 budget rule?
It is a budgeting method that allocates approximately 50% of take-home income to needs, 30% to wants, and 20% to savings and debt goals. You can adjust these percentages when your essential expenses are higher.
How much should I spend on rent in NYC?
A commonly used starting benchmark is approximately 30% of gross income. However, this is not a universal affordability guarantee. Consider your take-home pay, debt, household expenses, and savings needs before signing a lease.
Which NYC borough is the cheapest to live in?
There is no permanently cheapest borough for every household. Rent, neighborhood, apartment size, transportation, and household requirements all affect total expenses. Compare actual housing and commuting costs before making a decision.
How much should I save for emergencies?
A common target is three to six months of essential expenses. You may need a larger reserve if you have irregular income, dependents, or limited employment security.
Can I use the budget planner if I am paid every two weeks?
Yes. Convert your actual biweekly take-home pay into an average monthly amount by multiplying it by 26 and dividing by 12. Remember that some months include three biweekly paychecks, so keep a separate plan for those additional-paycheck months.
Does this calculator calculate exact New York income tax?
No. The budget planner is designed to organize your income and expenses. It does not replace a full Federal, New York State, or NYC income tax calculator. Use your actual payroll take-home amount or a verified tax estimate.
Is my financial information sent to a bank or AI company?
The calculator is designed to perform its budgeting calculations locally in your browser. It does not need bank credentials or an external generative AI connection. Avoid entering sensitive account details into any budgeting tool.
Can I use this calculator for a family budget?
Yes. You can enter household income and combined expenses to create a family budget. Include childcare, healthcare, groceries, education, transportation, and dependent-related expenses where applicable.
Final Thoughts: Build a Budget That Works for Your Life in New York
Managing money in New York is not about following a perfect percentage or cutting every enjoyable expense. It is about understanding your financial priorities and making decisions that fit your actual circumstances.
A useful budget should help you answer practical questions: Can I afford this apartment? How much can I save? Am I spending too much on transportation? How long will it take to build an emergency fund? What happens if my expenses increase?
The AI Budget Planner New York on NewYorkCalculator.com is designed to make those questions easier to explore. Start with your actual take-home income, enter your regular expenses, and adjust your plan until the numbers reflect a realistic monthly budget.
Review your plan regularly, use reliable financial information, and make changes when your circumstances evolve.
A better financial plan starts with understanding where your money goes.
About the Author
Junaidul Islam writes practical online guides and develops digital tools designed to help people make more informed everyday decisions. His focus is on making complex calculations easier to understand through accessible, user-friendly online resources.
Last updated: October 12, 2026
Editorial note: This article provides general educational information, not individualized tax, legal, investment, or financial advice. Calculator results are estimates based on user-provided information. Verify current rates, program eligibility, and tax obligations with the relevant official authorities.
Sources and further reading